
Is This Still The Best Reversal Strategy?

Today, we look at what we regard as the best reversal strategy.
For decades, markets have shown a surprisingly persistent tendency to rebound early in the week after a rough start. It is simple and easy to backtest (and to trade).
Despite being one of the oldest short-term edges in the stock market, the Turnaround Tuesday effect still refuses to die. We first mentioned it (and backtested it) on our website as far back as 2012.
The Turnaround Tuesday strategy is one of the classic mean-reversion patterns in the stock market. The idea is straightforward: when the market falls (sharply) on Monday, there is often a higher-than-average chance of a rebound on Tuesday.
It sounds almost too simple. But that is exactly why it is so interesting.
Many trading strategies are overcomplicated. They rely on dozens of indicators, filters, and rules that make them look impressive but hard to trade in real life.
Turnaround Tuesday is different. It is built on a basic market behavior: short-term fear often gets overdone, and when traders rush to sell at the beginning of the week, the market can quickly snap back.
In this article, we look at how it can be tested and whether it still offers a tradable edge today. Because sometimes the best reversal strategy is not the newest one. It is the one that has survived long enough to prove it still matters.
Let’s backtest it:
Is This Still The Best Reversal Strategy?
The strategy has worked well for the S&P 500 over four decades, including the 2008 financial crisis, so this time we backtest SSO. SSO is the ticker code for an ETF that uses 2x leverage for the S&P 500, so beware the risks.
This is the performance:
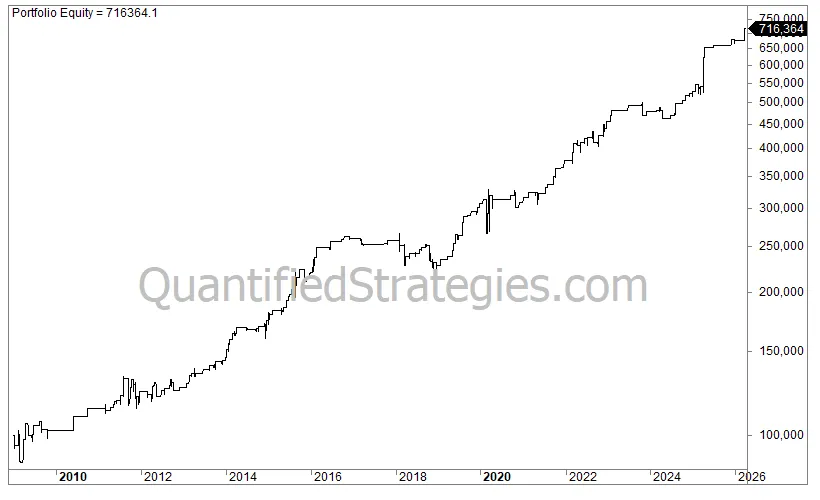
Performance
- No. of trades: 181
- Average gain per trade: 1.2%
- Win ratio: 70%
- Profit factor: 2.5
- Annual returns (CAGR): 12%
- Exposure/time in the market: 10%
- Risk-adjusted return: 111% (CAGR divided by time spent in the market (0.1))
- Max drawdown: % (buy and hold 59%)
Trading Rules
We made the following rules:
– Today is Monday;
– The close must be lower than Friday’s low.
– Sell at the close when it ends above yesterday’s high;
– Or after 4 trading days (On Friday).
Amibroker code:
UpVolume = IIf(C>Ref(C,-1),V,0);
DownVolume = IIf(C
sellPrice=Close ;
Short= Cross(VolumeRatio,6) AND Day()<25;
shortPrice=Close;
Cover=C