252-Day Low Trading Strategy For Stocks (Complete Amibroker Code With Backtest and Trading Rules)

Is it a good idea to buy stocks setting 252-day lows? In this article, we backtest a 252-day low trading strategy for stocks.
Key Takeaways
- Buying 252-day lows performs very poorly
- Strategy delivers negative long-term returns
- Annual return of minus 7.7 percent
- Extremely large drawdowns up to 89 percent
- Low win rate around 35 percent
- Capital efficiency remains relatively low
- Downtrend stocks continue underperforming
No, it’s not a good idea to buy stocks that set new 252-day lows. The 252-day low trading strategy for stocks returned a negative 7.7% annually while using, on average, 40% of the capital.

252-day low trading strategy – trading rules
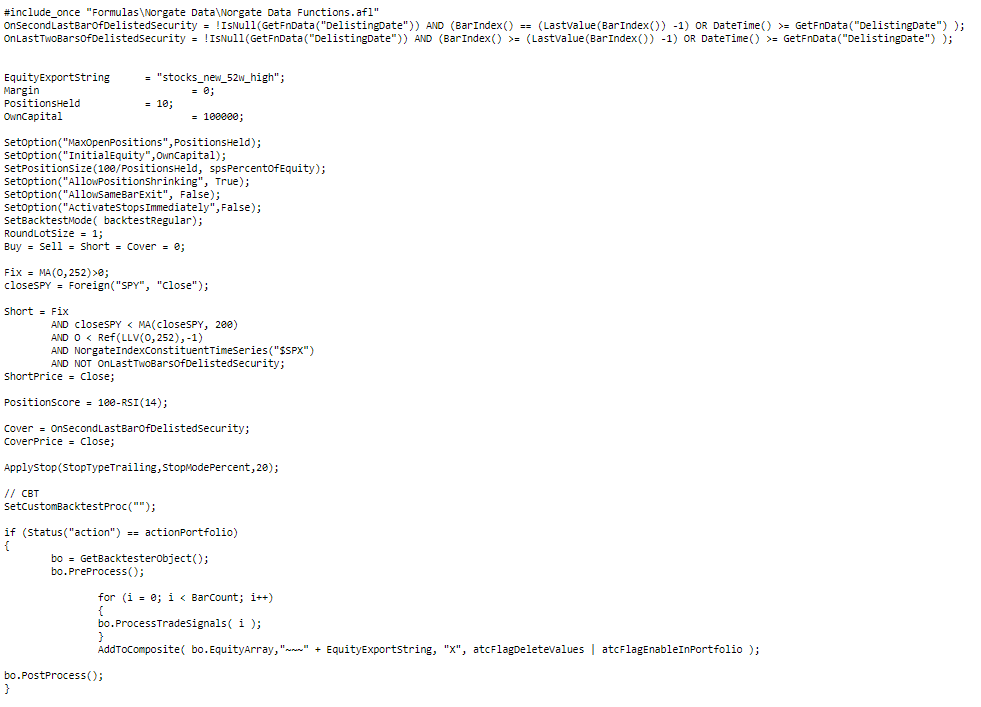
We make the following trading rules (with complete code for Amibroker):
You find the trading rules at the bottom of the article
For this backtest we used Norgate survivorship free data and we the rotation function in Amibroker. We hold a max of ten positions each time. Commissions and slippage are not included in the backtest.
When we backtested the strategy on the stocks in the S/P 500 we got the following equity curve:

The trading statistics and performance read like this: 864 trades, annual return of minus 7.7%, 35% win rate, max drawdown is 89%, and you are invested 40% of the time.
The image below shows the full summary of the trading performance:

The code in Amibroker looks like this: