

A Pair Trade in SPY And TLT: Testing Pairs Trading Strategies in Bonds and S&P500 – Backtest and Trading Rules

A Pair Trade in SPY And TLT (Pairs Trading Strategies). A few days ago, we witnessed major moves in both long-term Treasuries (TLT) and the S&P 500 (SPY). That is not abnormal: when the going gets tough in stocks, many investors rotate into “safe” Treasuries. We write “safe” because over the long-term, especially now, you are bound to lose your purchasing power over the next decade(s) by owning government bonds. Let’s backtest a pair trade in Bonds and S&P500.
In this article, we test a pair trade in SPY and TLT. Is a pair trade in SPY and TLT profitable after big moves in opposite directions? We test this hypothesis. As it turns out, this is not a tradeable strategy.
Key Takeaways
- Strategy pairs stocks and bonds for market neutrality
- Trade long SPY and short TLT
- Entry based on abnormal opposite price movements
- Backtest shows low returns and inconsistency
- Win rate decent but profits remain small
- Changing parameters does not improve performance
- Strategy becomes worse over longer holding periods
- Not a reliable or tradeable pairs strategy
What is a pair trading strategy?
First off, you might wonder what a pair trading strategy is, often called spread trading. We started our trading career with pairs trading some 20 years ago and in the article below we explain the pros and cons of pairs trading:
The main idea is to be somewhat “neutral” against erratic moves in the market.
We have previously written another article about a potential pair trade in ETFs:
The pair trade in SPY and TLT:
On Friday the 18th of June both the S&P 500 and Treasury bonds made huge moves in opposite directions. Both ETFs reversed the following Monday after the weekend.
This is what happened on Friday the 18th of June 2021 until Monday 21st:
This is SPY from Friday 18th to Monday 21st:
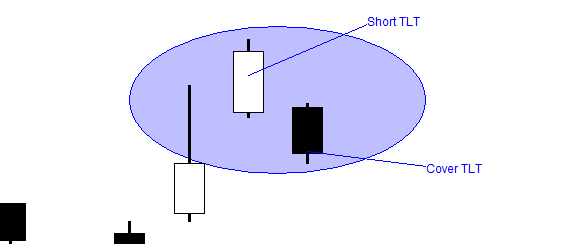
This is TLT from Friday 18th to Monday 21st:

At the close on Monday 21st of June, the S&P 500 had risen 1.43% from the close on Friday and the TLT fell 1.67% and both reversed the moves from Friday.
Was this a coincidence? How has such a trade performed in the past?
Let’s test the following pair trading strategy in SPY and TLT:
When the S&P 500 falls more than “normal” we go long SPY, and we short TLT if it rises more than “normal”. Both have to happen on the same day.
Here are the rules for our pair trading strategy:
You find the trading rules at the bottom of the article
This is a pretty simple pair trade, and probably not one of the most rational or intuitive of trades either.
Let’s test the result by holding the pair overnight from today’s close until tomorrow’s close (we are long SPY and short TLT). This is the equity curve:
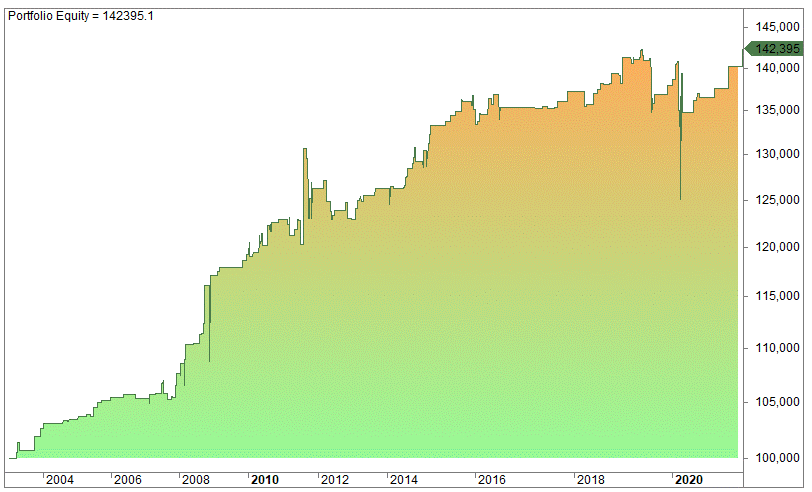
The equity curve shows 100 000 compounded from 2003 until June 2021. No commissions and slippage included.
As the equity curve shows, the strategy is a bit erratic and not very consistent and the pair strategy didn’t work well in the last years.
- CAGR is 1.93%
- 416 trades (208 long and short)
- The average gain per round trip is 0.18%
- 60% win ratio
- The average winners and losers are equal in %
- The profit factor is 1.42
All in all, not a tradeable strategy.
Does it get any better if we change the parameters?
Changing the holding period for the SPY/TLT pair trade:
The best exits are at the close of the third day (0.26% average), but in general, the results are pretty similar less than 5 days. Above 5 days the results get worse.
Changing the movement criteria for the SPY/TLT pair trade
If we change the criteria for movement, both higher and lower than 1.25, the results don’t improve much either way, unfortunately.
If you want the Amibroker code for this strategy plus the 70+ other strategies on this page, you can order here:

Relevant article:
Some years back we published another SPY and TLT strategy that has performed pretty well, but this is a rotation strategy, not a pair strategy:
FAQ:
– What happened in the market on June 18th, 2021, that led to a pair trade opportunity in SPY and TLT?
On June 18th, 2021, both the S&P 500 (SPY) and Treasury bonds (TLT) experienced significant moves in opposite directions. The S&P 500 rose 1.43%, while TLT fell 1.67%. The article explores whether such events create profitable opportunities for a pair trading strategy.
– How is the pair trading strategy in SPY and TLT tested in the article?
The pair trading strategy involves specific rules. When the S&P 500 falls more than 1.25 times the 50-day average of the high-minus-low (H-L), and TLT rises more than 1.25 times the 50-day average of the H-L on the same day, a long position in SPY and a short position in TLT are initiated. Positions are closed x-days later.
– Is the pair trade in SPY and TLT a profitable strategy?
The tested pair trading strategy did not prove to be consistently profitable. The equity curve showed erratic behavior with a CAGR of 1.93%, a 60% win ratio, and an average gain per round trip of 0.18%. Despite variations in parameters, the strategy did not demonstrate significant improvement.