
The 5-Day Low of The Range Strategy in 2026 – Backtest and Trading Rules

The 5-Day Low of The Range Strategy, with its simple criteria of IBS lower than 0.25 and the close lower than the lowest low of the previous 5 days, has shown remarkable results.
Over the period from January 1993 until today, it has yielded 309 winners out of 517 trades, with an average return of 0.46% per trade—far exceeding the average return for any 5-day period.
Its profitability peaks between 3-7 days, offering a 10.76% annualized return compared to buy and hold strategies. Furthermore, it can potentially be adapted for short selling, albeit not the same impressive returns because short is very difficult to trade. This strategy underscores the potential for consistent profits in trading with minimal complexity.
Key Takeaways
- Simple mean reversion strategy with minimal rules
- Uses IBS and five-day low criteria
- High win rate with consistent trade profits
- Average returns exceed typical five-day performance
- Best results occur within three to seven days
- Outperforms buy-and-hold on annualized basis
- Strategy simplicity reduces execution complexity
The 5-Day Low of The Range Strategy
Here is the strategy in plain English:
Trading Rules
You find the trading rules at the bottom of the article
This is a very simple strategy. No fancy tools and hardly any calculations.
This is the result from January 1993 until today:
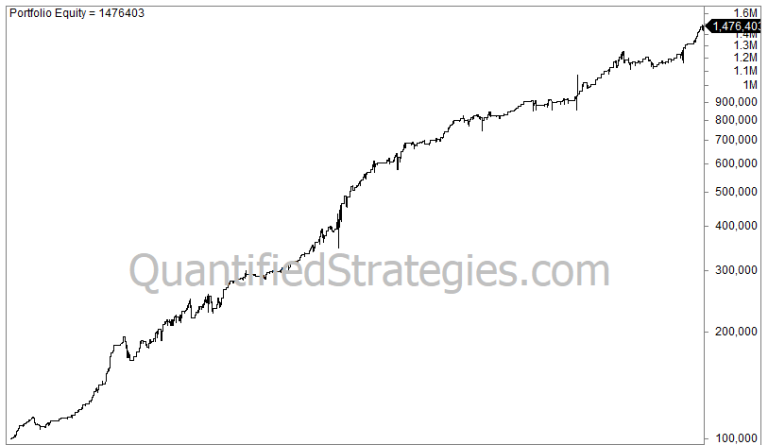
- 414 trades,
- 305 winners,
- Average of 0.7% per trade (after 0.03% in commission and slippage per trade),
- Max drawdown is 20%.
This is way above the average return for any 5-day period which is 0.11% in the same period. However, the strategy has not worked so well lately. The win ratio is 73%, and the average winner is bigger than the average loser.
If you would like to have the Amibroker and Tradestation code for this strategy plus 300+ other free trading strategies published on this website, you must become a member.
For more trading strategies, please click here:
- Free trading strategies
- Monthly trading edges (subscription service)
What are the results of implementing the The 5-Day Low of The Range Strategy?
During this period, the strategy resulted in 102 trades, with 68 of them being winners. The average return per fill was 0.98%, significantly outperforming the average return for any 5-day period, which was 0.11% during the same time.
How does The 5-Day Low of The Range Strategy compare to buy and hold?
The strategy’s profitability is highest over 3-7 days. Exiting after five days can result in a 10.76% annualized return, outperforming buy and hold, which is held for a significantly longer period. However, lately the strategy has not performed well.
Is The 5-Day Low of The Range Strategy adaptable for short selling, and what criteria are involved in shorting?
The strategy can be adapted for short selling by using a specific criterion on today’s range, such as 0.75, to identify short opportunities, but short strategies are much less profitable than longs.