
A Rules-Based Momentum Strategy

A Rules-Based Momentum Strategy is a systematic approach to responding to shifts in market leadership without relying on predictions or short-term noise.
By following a consistent process, the strategy aims to keep portfolio decisions disciplined and repeatable and to take advantage of the momentum effect in the markets.
A Rules-Based Momentum Strategy for Changing Markets
We backtested the trading rules on the following ETFs:
- SPY: US stocks
- GLD: Gold
- TLT: US long-term bonds
- DBC: Commodities
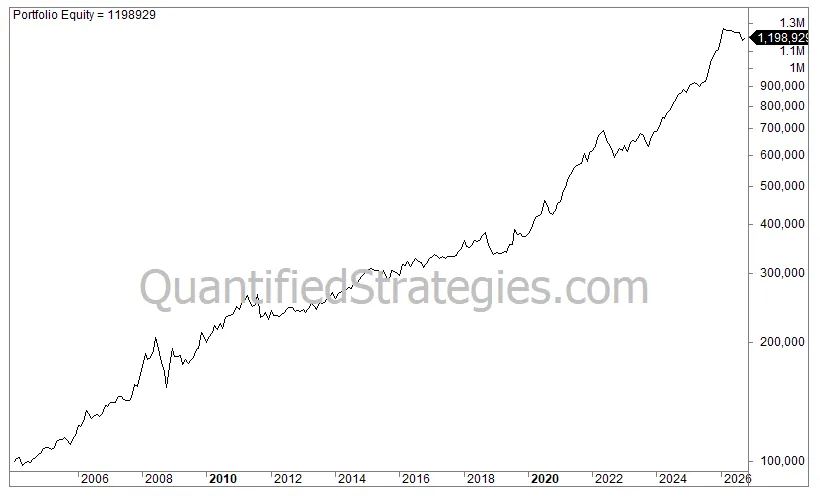
From 2004, we get the following result (monthly bars):
Performance
- No. of trades: 68
- Average gain per trade: 9%
- Win ratio: 54%
- Profit Factor: 4
- Annual returns (CAGR): 11.7%
- Exposure/time in the market: 97%
- Risk-adjusted return: 12% (CAGR divided by time spent in the market (0.97))
- Max drawdown: -25%
Exposure is not 100% due to rebalancing.
Trading Rules
We have the full code for this strategy for TradingView, Python, Metatrader, Ninjatrader, Tradestation, and Amibroker on our website – Platinum/Annual membership:
We made the following trading rules:
🔒 These trading rules are for members only.